In 1985, two men sat in a small New York office with a big idea and very little else. Stephen Schwarzman was thirty-eight. His partner, Peter Peterson, was a former United States commerce secretary and the former chairman of Lehman Brothers. Between them they had four hundred thousand dollars of starting capital, a two-person staff, and no investors, no track record, and no real proof that anyone wanted what they planned to sell. In the early days they worked brutal hours and sometimes slept at the office.
They named their firm with a small private joke. Schwarz is the German word for black. Peter, from the Greek petros, means stone or rock. Stitched together, the two founders’ names became Blackstone.
Four decades later, that four-hundred-thousand-dollar partnership would become the largest alternative asset manager the world has ever seen, the first of its kind to cross a trillion dollars in assets, a firm that owns more commercial real estate than almost anyone on Earth and reaches into the retirement savings of millions. This is the story of how two men turned a backwater corner of finance into its glittering center, and of the one decision, a quiet sale in 1994, that let an even larger giant slip through their fingers.
📄 Free Download · Company Research Sheet
Blackstone Research Sheet (PDF)
The moat, the meltdown, the Legendary Scorecard, the timeline, and the Move, Money and Mind lessons from this story. Free, no email required.
Two Men From Lehman
Schwarzman and Peterson had both just left Lehman Brothers, which had been sold to American Express, and they carried out the door something more valuable than money: reputation and relationships. Peterson brought a vast network of corporate and political connections and instant credibility. Schwarzman brought relentless drive and a dealmaker’s instinct. Their first business was humble, an M&A advisory boutique offering conflict-free advice to corporations at a time when the big banks were riddled with conflicts. The model worked. Early on they advised on the 1987 merger of the investment banks E.F. Hutton and Shearson Lehman, collecting a fee that helped keep the lights on.
But advice was never the real ambition. Schwarzman wanted to invest, to own, to put capital at risk and take a share of the upside. The advisory business was the bridge to something far larger.
The Pivot to Principal
The leap came when Blackstone set out to raise its first private equity fund, a pool of capital to buy companies outright. It was an audacious ask. Neither founder had a leveraged-buyout track record, and they were asking institutions to lock up money for years on faith. Fundraising was painful, with door after door closing, but they eventually closed a first fund of around eight hundred million dollars, a substantial sum for two men who had started with four hundred thousand. Blackstone was now a principal investor, buying companies, improving them, and selling them for a profit, taking a slice of the gains along the way.
From that base, Schwarzman expanded relentlessly into the spaces other firms found too hard or too dull. After the savings-and-loan crisis left a wreckage of distressed buildings, Blackstone built a real estate arm that would become the largest of its kind, eventually making the firm one of the biggest owners of commercial property anywhere. It moved into credit, into hedge fund solutions, into infrastructure and insurance. The unifying idea was simple and powerful: raise long-term capital, buy assets that do not trade easily on public markets, manage them patiently, and charge fees for doing so. Blackstone was not picking stocks. It was building an empire of things that almost never change hands.
Patient Capital. The whole machine rests on money that does not need to move. Long lock-ups and multi-year horizons let Blackstone buy what the crowd cannot hold, and be paid for the patience. The illiquidity that ordinary investors fear is the very thing that creates the premium.
The Name That Became a Fortune, and a Regret
In 1988, a young bond trader named Larry Fink came to Blackstone looking for backing to start a fixed-income business built around risk management. Blackstone provided the seed capital and took a fifty percent stake, and the new unit was christened Blackstone Financial Management. It grew quickly. By 1992 the business had taken a new name, BlackRock, keeping the Black as a nod to where it had begun. Then, in 1994, after a falling-out over equity and direction, the two sides parted, and Blackstone sold out in a deal worth about two hundred and forty million dollars.
It was, by the cold arithmetic of hindsight, one of the most expensive divestitures in the history of finance. The business Blackstone let go for two hundred and forty million dollars grew into the largest asset manager on the planet. By September 2026 BlackRock managed $15.5 trillion, about eleven times Blackstone’s assets, and on the stock market it was worth around $182 billion against Blackstone’s $144 billion. Schwarzman would later call the sale a major regret. The parent had given life to the child that would outgrow it.
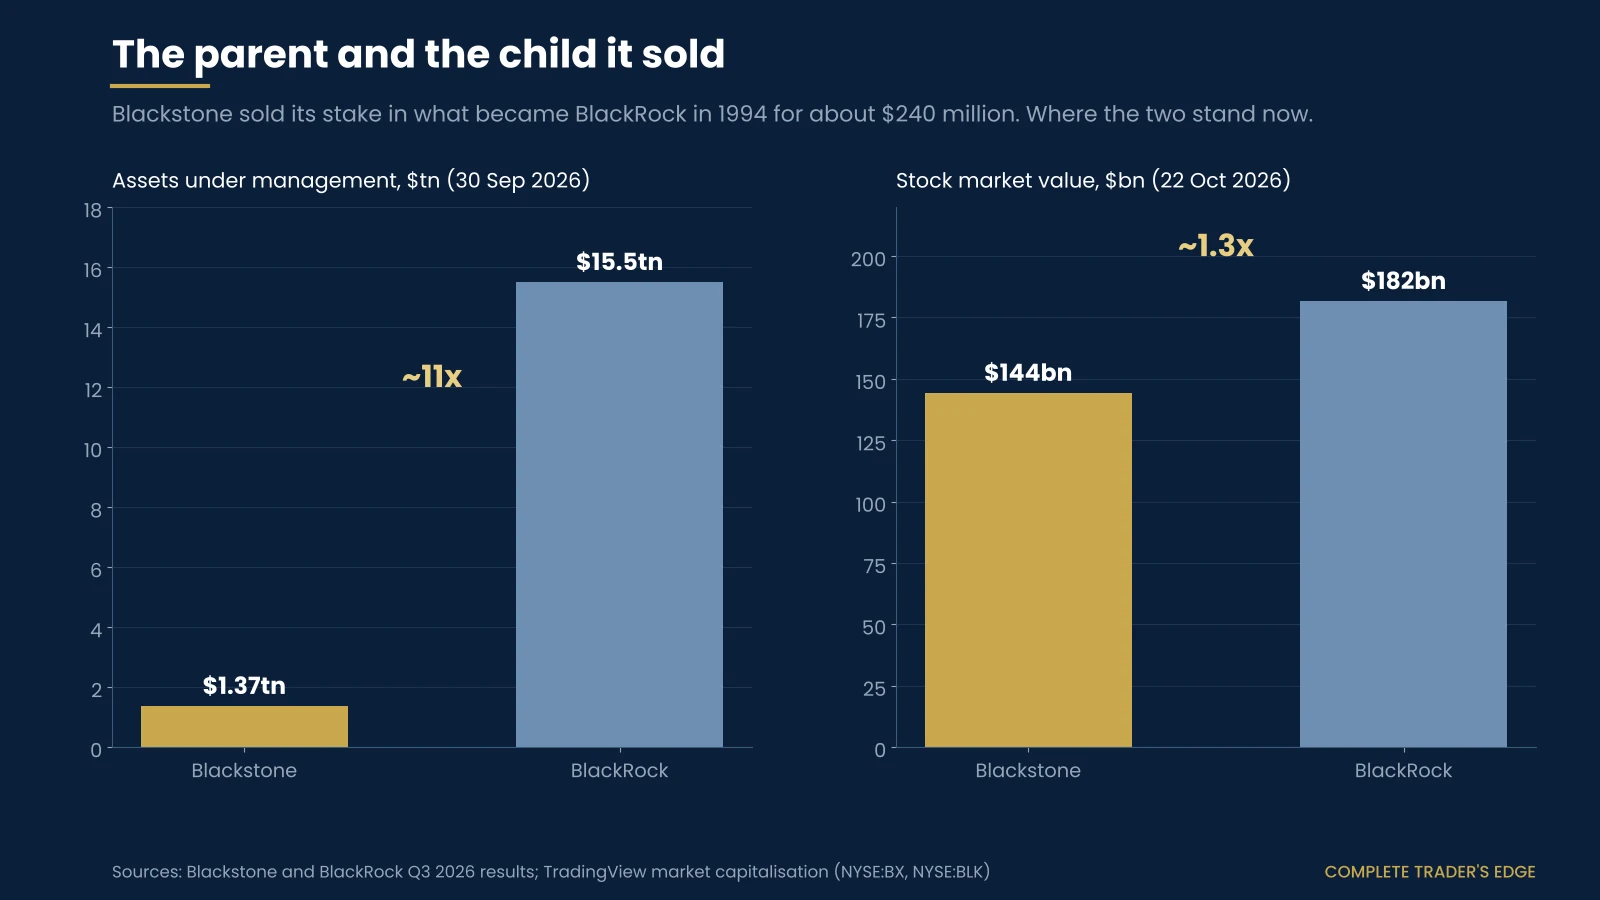
The chart carries a second lesson. Assets under management and business value are not the same thing. BlackRock’s trillions sit mostly in low-cost index funds; Blackstone’s smaller pool earns far richer fees per dollar. Size is the headline. Fee rate is the business.
Decision Point
The Decision Point. It is early 2007. Blackstone is enormously profitable and privately held. The credit markets are euphoric, asset prices are soaring, and the firm could go public at a spectacular valuation. You run Blackstone. The road forks.
A. Go public, cash in a fortune, and raise permanent capital, at the cost of quarterly scrutiny and the glare of public markets.
B. Stay private, keep control and secrecy, and forgo the windfall.
C. Wait for a calmer moment.
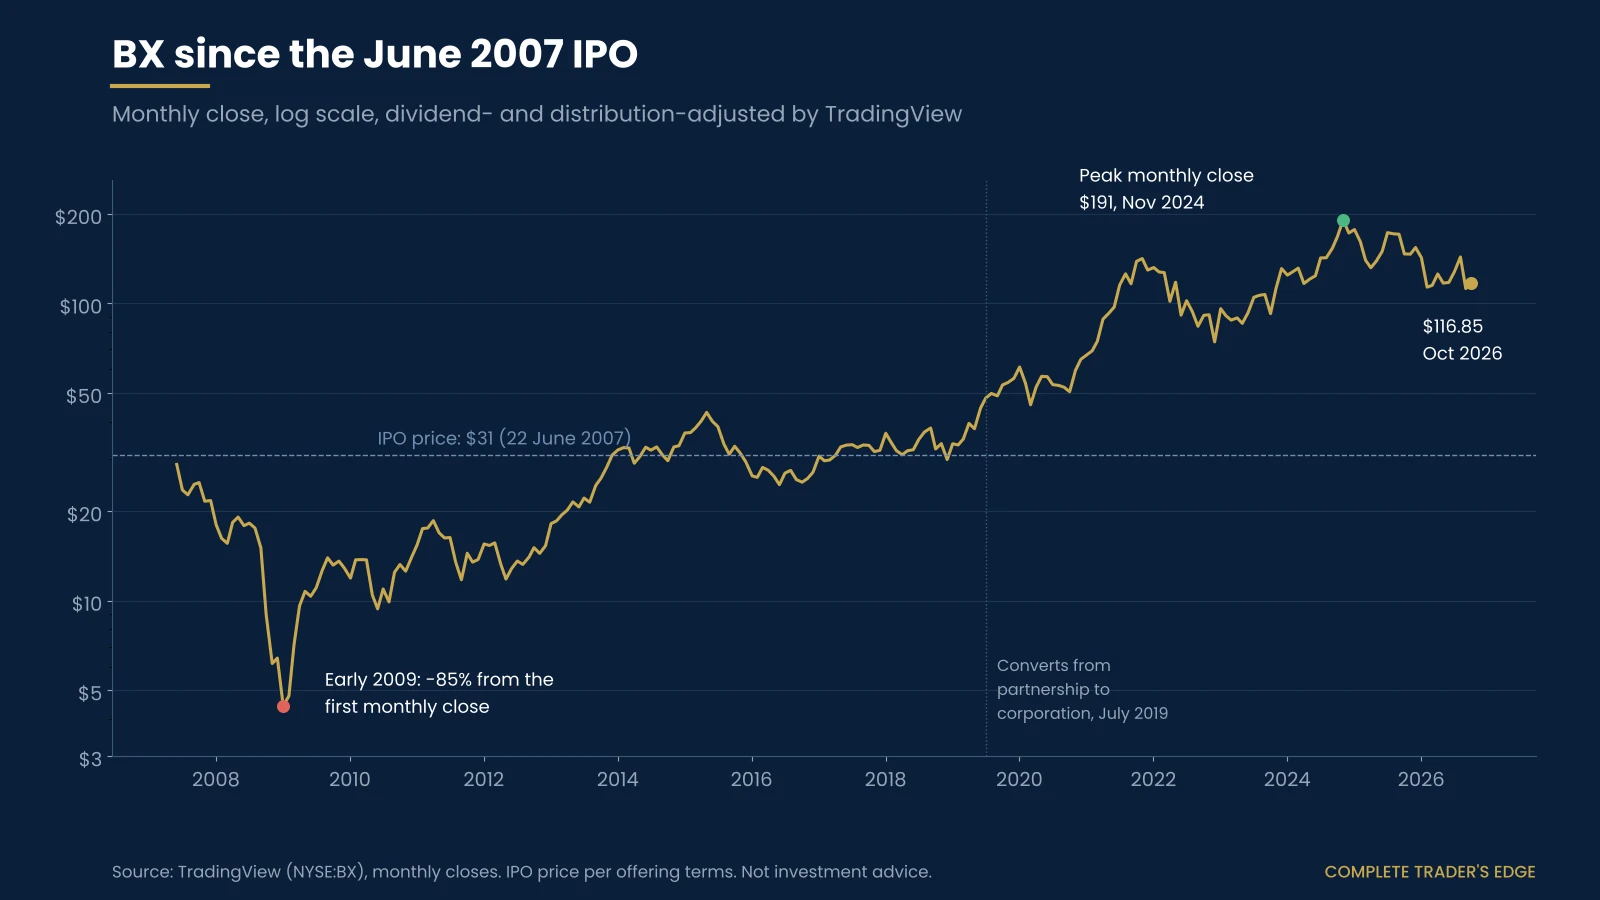
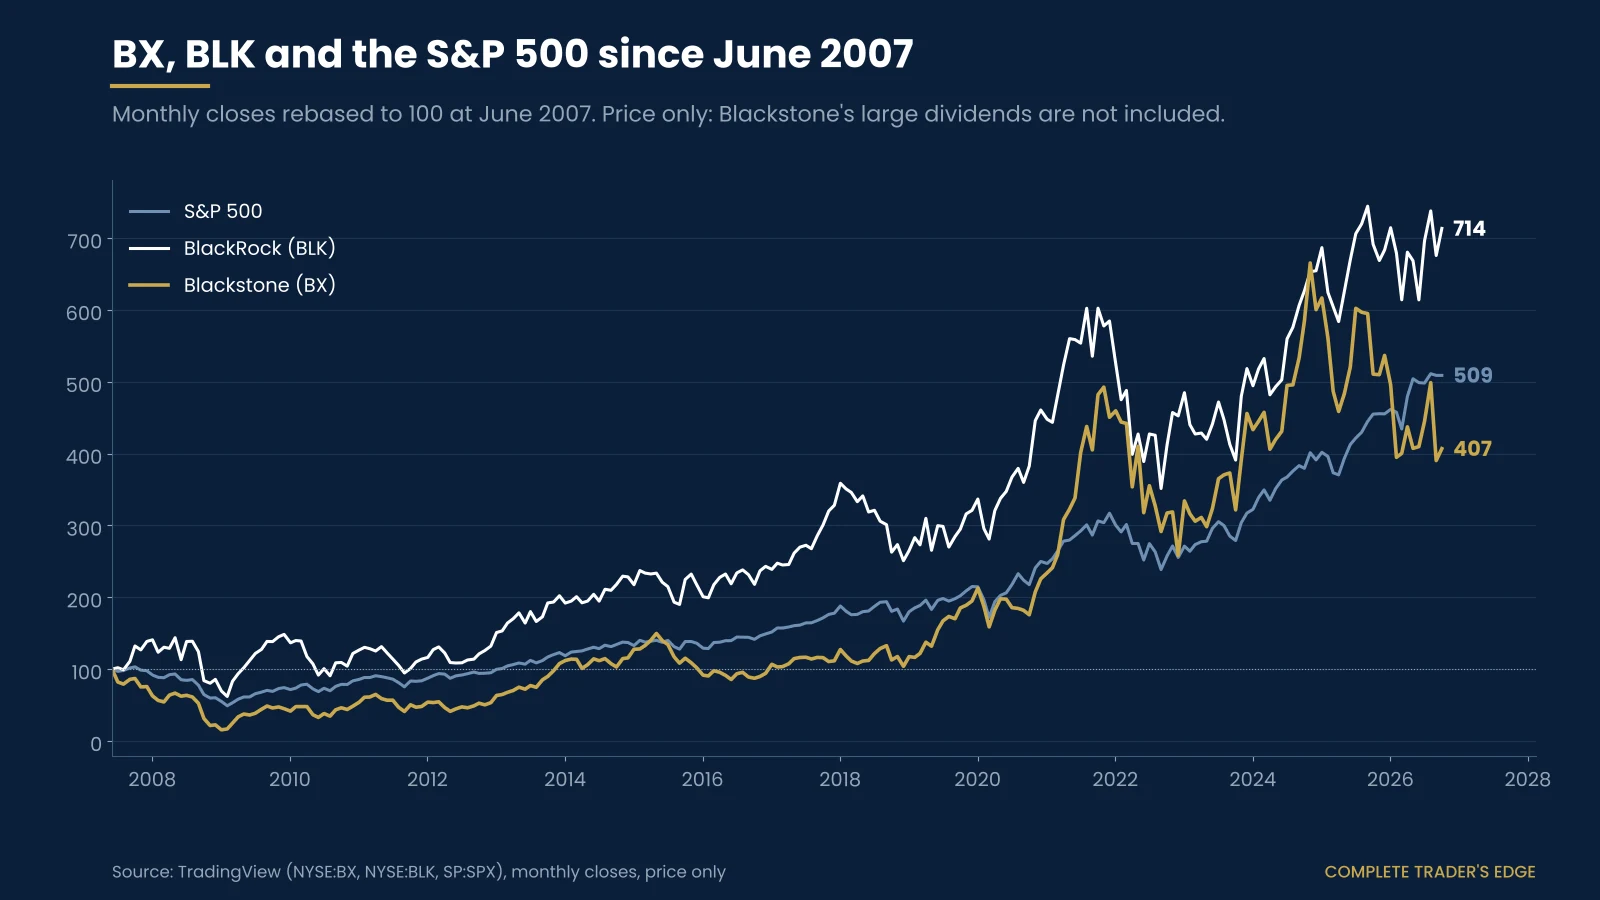
Blackstone chose to go public, in June 2007, the first major private equity firm to do so. The timing was almost perfectly bad: within about a year the financial crisis arrived and the shares collapsed far below the offer price. And yet it looks shrewd in the long run. Blackstone had locked in permanent capital and a public currency right before the storm, and used the wreckage to buy assets cheaply and grow enormously. This is a thought experiment about timing and permanence, not investment advice.
What Everyone Gets Wrong
Mistake #1: Thinking private equity is just corporate raiding and asset-stripping. The caricature is old. Reality: The crude buyout barons of the 1980s gave way to firms like Blackstone that mostly aim to buy, improve, and grow businesses and assets over years, because their returns and their reputation depend on it.
Mistake #2: Confusing Blackstone with BlackRock. The names are nearly identical and the history is shared. Reality: They are different firms doing different things. Blackstone owns hard assets and companies through private funds; BlackRock mostly manages public stocks and bonds, much of it through low-cost index funds.
Mistake #3: Reading the 2007 IPO as a top-tick blunder. The shares did crash. Reality: The firm thrived afterward, using permanent capital to buy cheaply in the crisis. Going public at the top looked like vanity and turned out to be foresight.
Mistake #4: Believing alternative assets are a niche. They once were. Reality: Blackstone helped drag private equity, private credit, and private real estate into the mainstream of how pensions, endowments, and now ordinary savers invest. The backwater became the center.
The Trillion-Dollar Machine
Blackstone’s genius was structural. By raising long-term and increasingly permanent pools of capital and charging fees to manage them, it built a machine that compounded almost regardless of the weather. The more assets it gathered, the more fees it earned, and the more credibility it had to gather still more. Under Jonathan Gray, who built the real estate juggernaut and became president, Blackstone reached deeper into the everyday economy, owning apartments, warehouses, data centers, and offices, and it pushed into the wealth of ordinary individuals through semi-liquid funds like its retail real estate vehicle BREIT and its private credit vehicle BCRED.
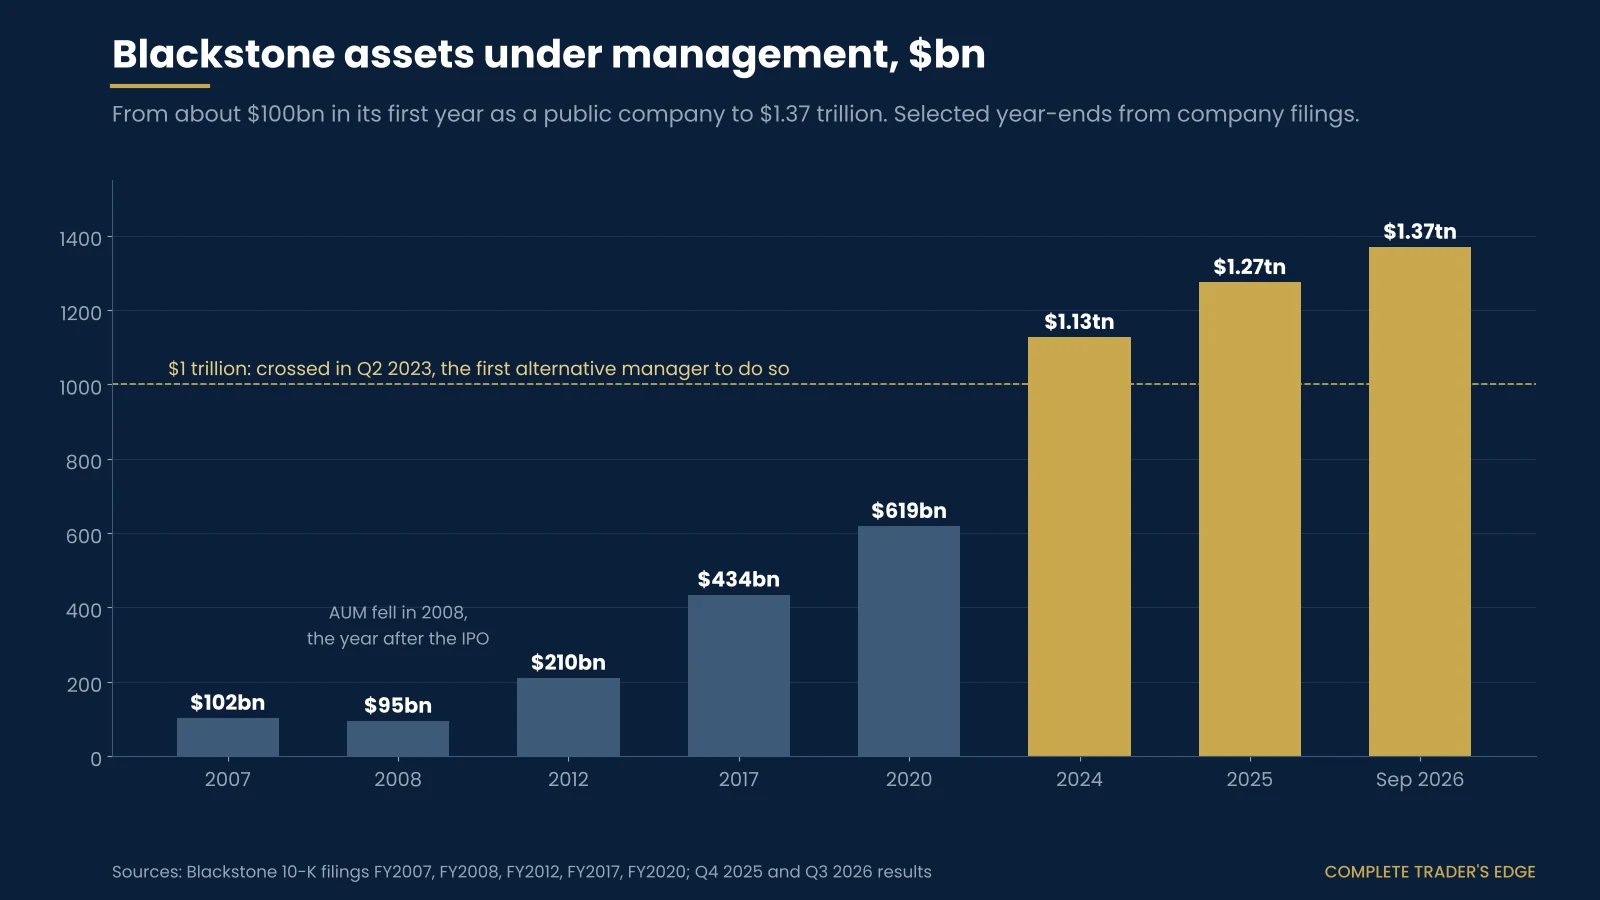
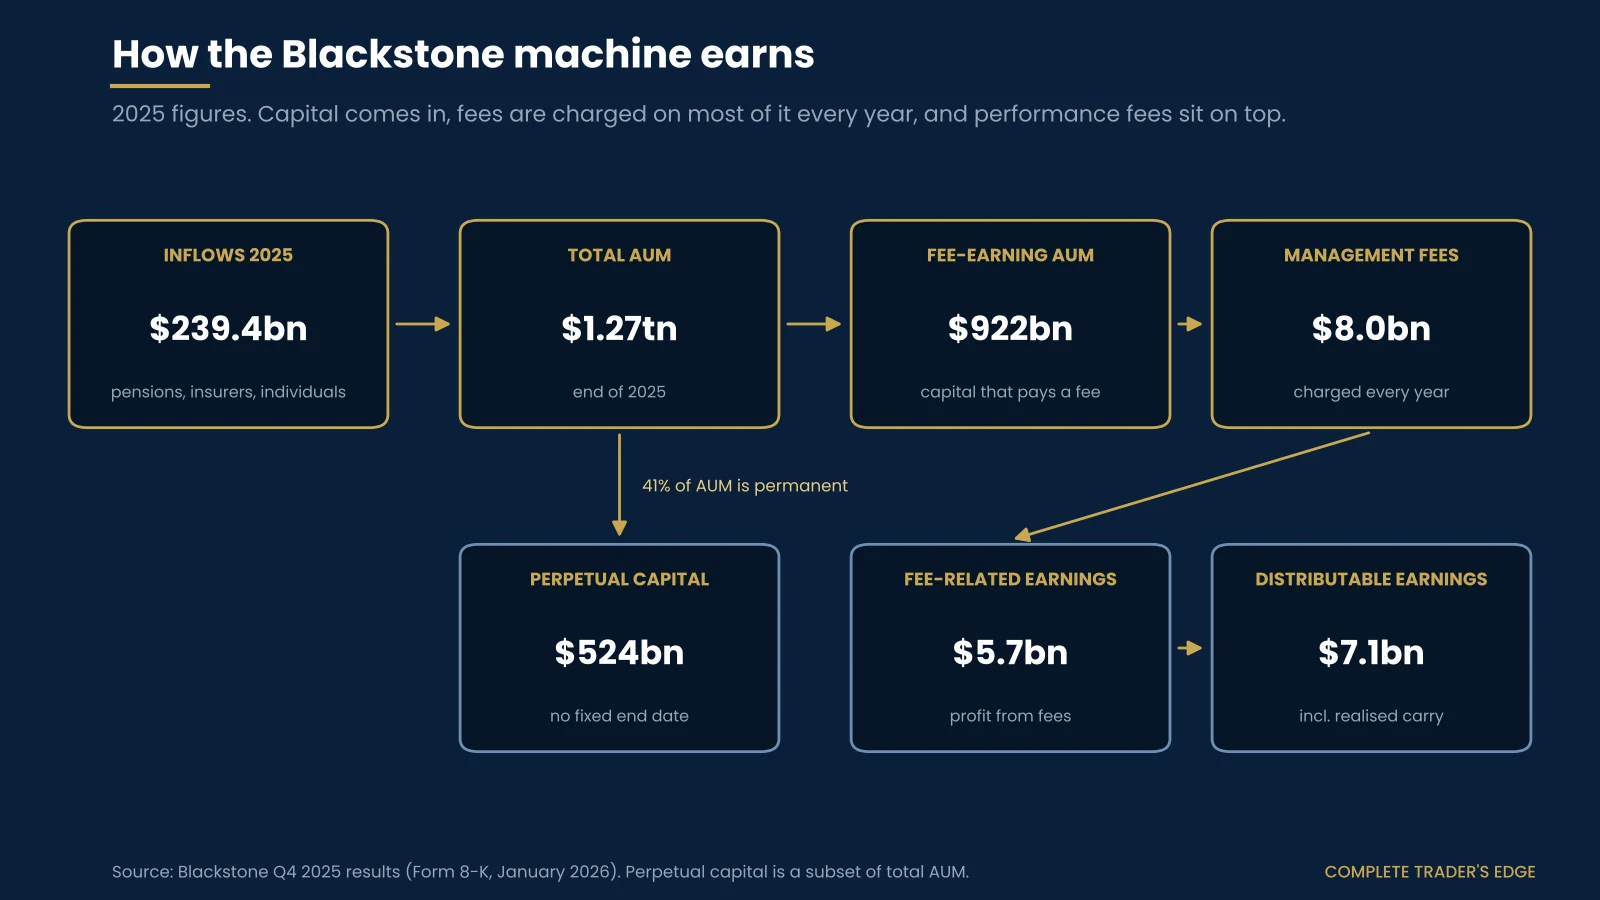
The machine is easiest to see in the numbers. In 2025 Blackstone took in $239.4 billion of new money. Of its $1.27 trillion in assets, $922 billion paid a fee, generating $8.0 billion of management fees. And $524 billion, about 41% of the total, was perpetual capital with no fixed date to hand back.
That reach into retail money produced the firm’s most public stress. In 2022 and 2023, as interest rates rose and property values wobbled, investors in BREIT asked for more of their money back than the fund was structured to return at once, and Blackstone limited withdrawals as the rules allowed. Critics called it a run; the firm called it the system working as designed. The episode passed, but it was a reminder that selling illiquid assets to individuals carries a particular kind of risk.
The Honest Present
In the second quarter of 2023, Blackstone became the first alternative asset manager in history to cross one trillion dollars in assets under management. It ended 2025 with $1.27 trillion and reached $1.37 trillion by September 2026, the largest such firm in the world. Schwarzman, its co-founder, remains chairman and chief executive, one of the wealthiest people in finance. The firm sits at the center of a vast shift, as capital pours out of public markets and into private ones, and Blackstone is the prime beneficiary.
And yet the questions multiply with the size. As trillions of dollars chase private assets, the high returns that justified the rich fees grow harder to find. The firm’s fortunes are tied to interest rates, to property values, and to the willingness of investors to keep locking up money for years. Blackstone built the road into alternative assets and now must drive it through a far more crowded landscape than the empty one it first found.
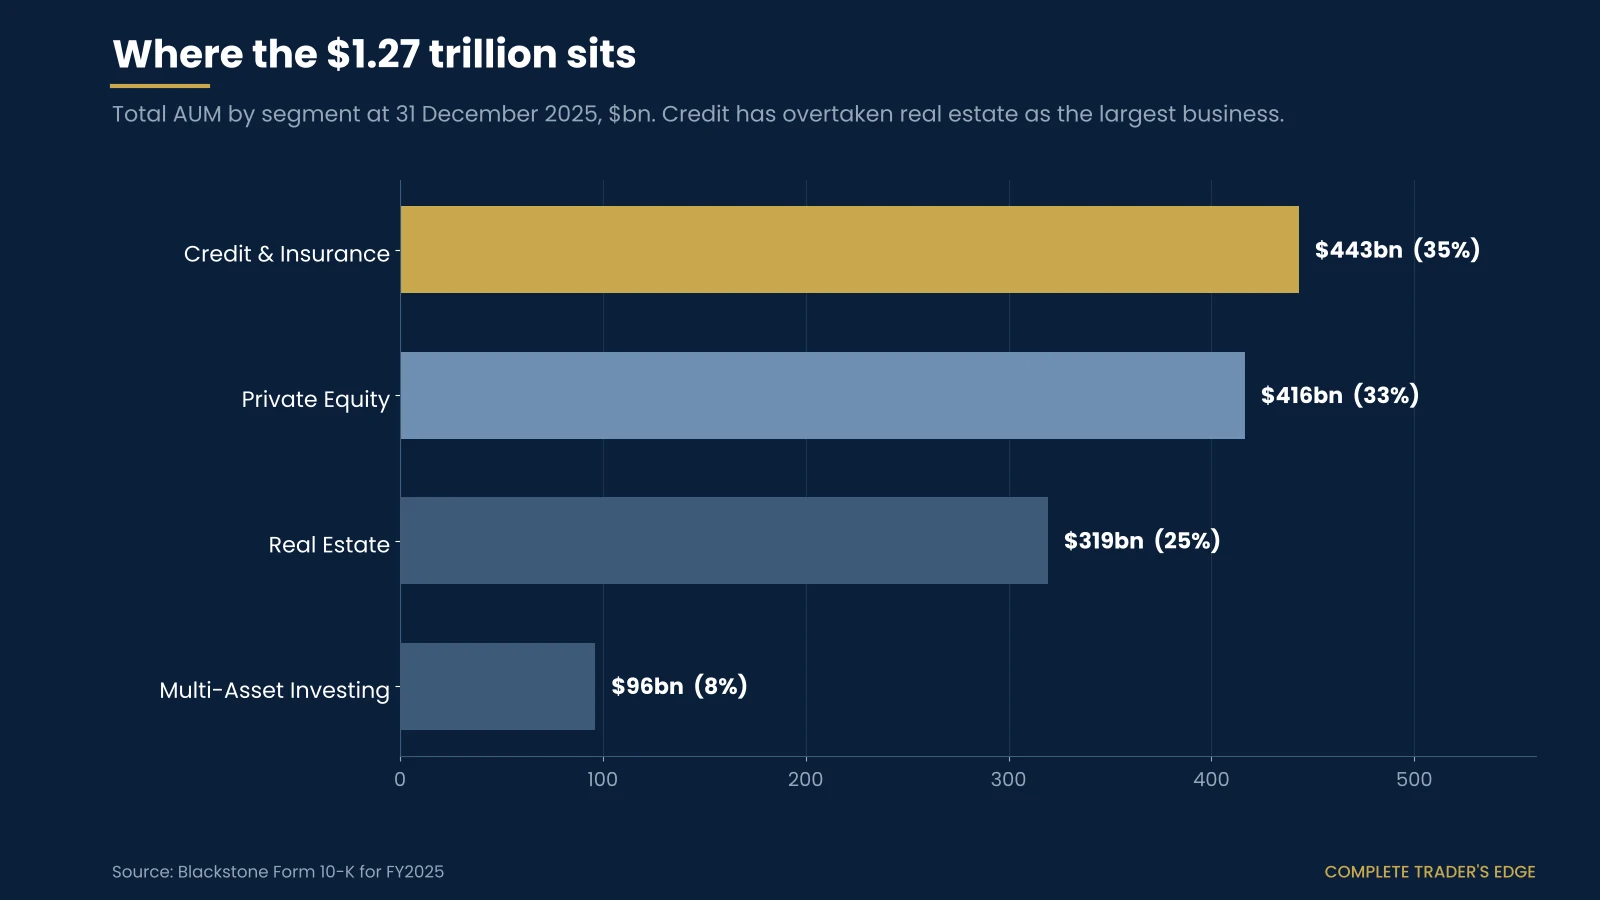
The crowding shows up in the share prices. Every large listed alternative manager has fallen this year, Blackstone included, as higher rates and slower deal exits weighed on the whole group.
Listed asset managers, 22 October 2026
| Company | Market value | 2026 to date | Trailing P/E |
|---|---|---|---|
| BlackRock (BLK) | $182bn | +4.3% | 26x |
| Blackstone (BX) | $144bn | −24.7% | 26x |
| KKR (KKR) | $83bn | −28.5% | 29x |
| Apollo (APO) | $67bn | −21.5% | 43x |
| Carlyle (CG) | $14bn | −34.6% | 40x |
Source: TradingView (market capitalisation, year-to-date price performance and trailing P/E). Price only; dividends excluded. Figures change daily.
Why This Matters to Investors
The Greatest Companies Thesis
Every legendary company begins with an idea that looks improbable.
Every one survives a stretch where failure looks inevitable.
Every one eventually reaches a point where success looks obvious.
The opportunity exists only in the space between the second and third.
Blackstone is capital allocation turned into a business. It does not make a product in the ordinary sense. It raises other people’s money, buys companies and assets, improves and holds them, and takes a share of the gains. That places it in the company of the great allocators, and it illustrates a truth that quiet compounders understand and frantic traders miss. The Greatest Companies thesis is that durable competitive advantage builds lasting wealth, and Blackstone’s advantage is scale and trust: the bigger it grows and the longer its record, the more capital it can raise, and the more capital it raises, the bigger it grows. The investor’s lesson is that some of the most durable fortunes in finance are built not by trading the liquid markets everyone watches, but by owning the things that almost never trade, charging patiently to manage them, and letting fees compound across decades. None of this is investment advice; it is a way of reading history.
Lessons in Order of Depth
Method: own what others cannot easily trade
Blackstone’s edge is the illiquidity premium. It buys assets, whole companies, vast portfolios of buildings, private loans, that cannot be sold at the click of a button, and it is paid for the patience and the lock-up that ordinary investors will not tolerate. The method is to look for the return that lives precisely where liquidity is scarce, where the crowd’s need for an easy exit creates an opportunity for those willing to wait.
Money: fees on permanent capital compound quietly
The deepest money at Blackstone is not any single brilliant deal. It is the management fee charged, year after year, on an ever-growing and increasingly permanent pool of capital. A modest percentage of a trillion dollars, collected annually almost regardless of markets, is one of the most powerful compounding machines in finance. The lesson is to notice who collects the steady toll, because the toll-taker often outlasts and out-earns the gambler.
Mind: patient capital is a temperament
Schwarzman built a firm around money that does not need to move. Long lock-ups, multi-year horizons, and a deep aversion to permanent loss are not just terms in a fund document; they are a temperament. The mindset is the willingness to be illiquid and patient when the rest of the market is obsessed with daily prices, and to treat the long horizon not as a constraint but as the source of the edge.
The deepest question: does scale eventually eat the returns?
Blackstone grew rich finding high returns in neglected corners of finance. But success attracts capital, and capital competes away returns. As alternative assets go mainstream and trillions of dollars crowd into private equity, private credit, and private real estate, the deepest question is whether the returns that once justified the fees can survive the flood of money chasing them. Can a firm built on the scarcity of patient capital keep its edge once patient capital is everywhere? That is the open question hanging over the entire industry Blackstone helped create.
The Legendary Scorecard
| Founder Vision | 9 |
| Innovation | 8 |
| Execution | 9 |
| Moat | 7 |
| Capital Allocation | 9 |
| Wealth Creation | 9 |
| Durability | 8 |
| Historical Importance | 8 |
| Overall | 8.5 |
The overall figure is an editorial verdict, not a weighted average. Blackstone earns top marks for capital allocation, execution, and wealth creation, because it built a new asset class and a compounding machine from four hundred thousand dollars. It scores a touch lower on moat, because the alternative-asset business is fiercely competitive and increasingly crowded, and an advantage built on scale and reputation is real but not impregnable.
At a Glance
| Founded | 1985, in New York |
| Founders | Stephen Schwarzman and Peter Peterson, with $400,000 |
| Name origin | Schwarz, German for black, plus Peter, from the Greek for stone |
| Core business | Alternative assets: private equity, real estate, credit, infrastructure |
| Defining trait | The first alternative manager to cross $1 trillion in assets |
| Famous offshoot | Seeded BlackRock in 1988, sold the stake in 1994 for about $240 million |
| Went public | June 2007, the first major private equity firm to do so |
| Key leaders today | Stephen Schwarzman, chairman and CEO; Jonathan Gray, president |
| Status | Operating, listed as NYSE: BX |
Timeline
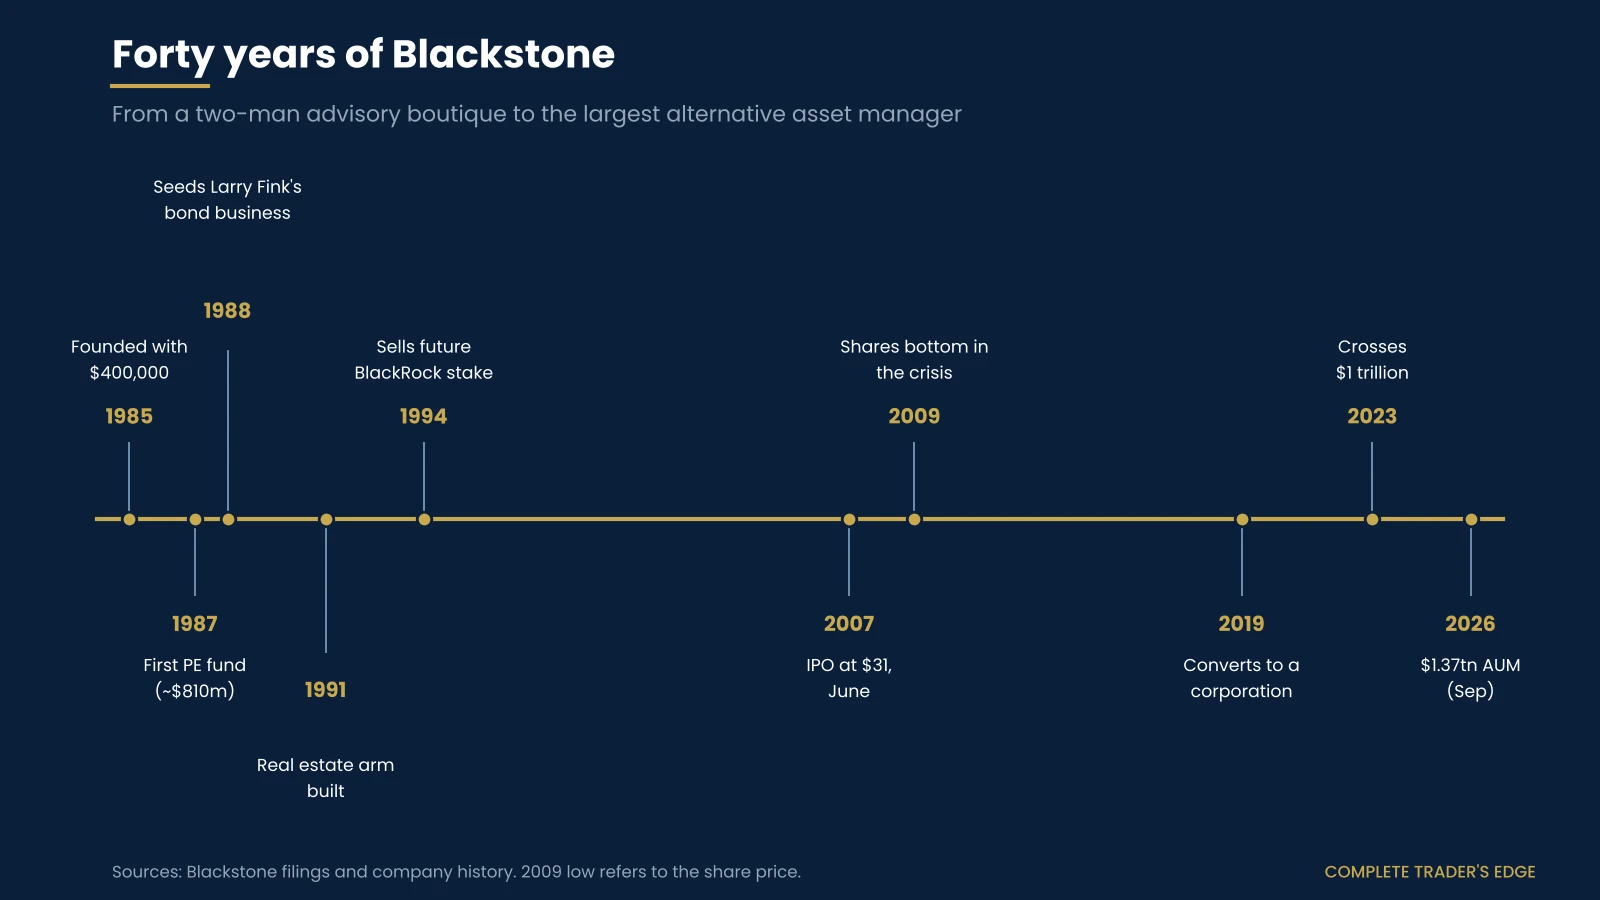
- 1985: Stephen Schwarzman and Peter Peterson found Blackstone with $400,000
- 1987: Blackstone raises its first private equity fund, and the market crashes on Black Monday
- 1988: Blackstone seeds Larry Fink’s bond business, the future BlackRock
- 1991: Blackstone builds its real estate arm amid the savings-and-loan wreckage
- 1994: Blackstone sells its stake in the future BlackRock for about $240 million
- 2007: Blackstone goes public in June, the first major private equity firm to do so, near the market top
- 2008: the financial crisis sends its shares far below the IPO price
- 2023: Blackstone becomes the first alternative manager to cross $1 trillion in assets
- 2025: Blackstone ends the year with $1.27 trillion of assets, the largest alternative asset manager in the world
- 2026: assets reach $1.37 trillion by 30 September
Key Numbers
$400,000 the starting capital in 1985
About $810 million the size of the first private equity fund
About $240 million what Blackstone sold its future-BlackRock stake for in 1994
2007 the year of the landmark IPO, near the market top
2023 the year Blackstone first crossed $1 trillion in assets
$1.37 trillion assets under management at 30 September 2026
Related Reading
Blackstone is one of the great capital allocators, and it sits beside others in this collection. Read how BlackRock, the bond shop it seeded and then sold in 1994, grew into the largest investor on Earth and dwarfed its former parent. See how Berkshire Hathaway built a very different kind of allocation machine, compounding inside a single permanent company rather than across a stack of funds. And study how Visa earns a steady toll on the flow of money, much as Blackstone earns a steady fee on the stock of it. For the full collection, see our Greatest Companies of All Time hub.
Go Deeper
Blackstone is a study in patient capital, in the illiquidity premium, and in the quiet power of compounding fees on a permanent pool of money. Those are the same forces that separate investors who think in decades from traders who think in minutes, and the book teaches you the discipline to value patience, to understand where returns actually come from, and to recognize the difference between owning an asset and merely renting a price.
★ Now in Kindle, Paperback & Hardcover
Greatest Companies
This story is one of fifty-one. The full book reads every legendary company through a single lens — Moat, Meltdown, Machine — from Standard Oil to SpaceX. Fifty-one companies, eight kinds of moat, one framework.
Kindle · $9.99 →
Paperback · $24.99 →
Hardcover · $34.99 →
Explore the Book →
This article is part of the Greatest Companies series, adapted from the book Greatest Companies, now available on Kindle.
Frequently Asked Questions
When was Blackstone founded, and by whom?
Blackstone was founded in 1985 by Stephen Schwarzman and Peter Peterson, both former Lehman Brothers executives, with $400,000 in seed capital. The name combines Schwarz, German for black, with Peter, from the Greek petros, meaning stone. It began as a mergers-and-acquisitions advisory boutique before moving into principal investing.
What does Blackstone actually do?
Blackstone is an alternative asset manager. It raises long-term capital from institutions and increasingly from individuals, and invests it in assets that do not trade easily on public markets: whole companies through private equity, commercial real estate, private credit, infrastructure, and insurance. It earns fees for managing that capital and a share of the profits.
Is Blackstone the same as BlackRock?
No. They share a history and a near-identical name but are separate firms. BlackRock began inside Blackstone in 1988 as a bond business, split off in 1994, and became the world’s largest manager of mostly public stocks and bonds. Blackstone focuses on private, alternative assets. BlackRock is far larger by assets under management.
How big is Blackstone?
In the second quarter of 2023 Blackstone became the first alternative asset manager to cross one trillion dollars in assets under management. It managed $1.37 trillion at 30 September 2026, making it the largest alternative investment firm in the world. It is one of the biggest owners of commercial real estate anywhere.
Why is Blackstone’s 1994 sale of BlackRock famous?
In 1988 Blackstone seeded Larry Fink’s bond business and took a large stake. In 1994 it sold out in a deal worth about $240 million. The business, by then named BlackRock, grew into the largest asset manager on Earth, with $15.5 trillion under management in September 2026, about eleven times Blackstone’s assets, and a larger stock market value. Co-founder Stephen Schwarzman has called the sale a major regret.
 The Complete Trader's Edge
The full Mind · Method · Money framework. 70 chapters.
View on Amazon →
 Market Mayhem
400 years of bubbles, crashes, and the pattern that keeps repeating.
Buy on Amazon →
 Greatest Companies
How the world's greatest companies were built — and what traders learn from them.
View on Amazon →
 Greatest Traders
Eighty-six lives that explain the markets — Livermore to Madoff, told with the losses left in.
View on Amazon →